


Weekly: China's thermal coal price decline narrows as resistance grows
- Opinion
- Price
- Consumption
- Stock
- Thermal Coal
- Coal
sxcoal.com1373 words66 reads


China's domestic thermal coal market continued its decline last week due to slow destocking at northern ports and weak downstream demand. The overall downward pace narrowed at both ports and production areas amid growing seller resistance; some mines even tested moderate upticks backed by rebounding purchases.
The imported thermal coal market diverged. While high-CV grade kept falling amid loose supply, low-CV grade stabilized on the back of utility tenders and price advantage following reduced freight rates and strengthening of the Chinese yuan.
Sxcoal CCI Index
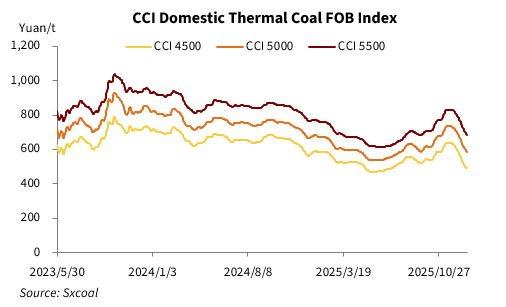
On December 26, the CCI index for 5,500 Kcal/kg NAR domestic spot coal stood at 682 yuan/t FOB northern China port with VAT, falling 34 yuan/t week on week, while the CCI index for 5,000 Kcal/kg NAR domestic coal was also down by 28 yuan/t from a week earlier to 586 yuan/t, the lowest levels in over three months.
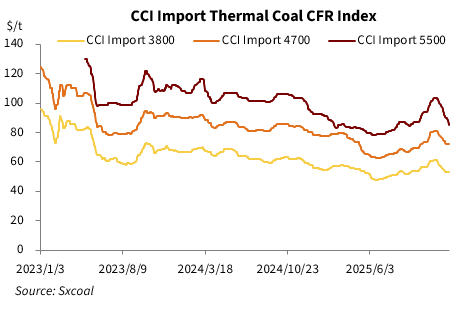
On the same day, the CCI 5500 Import index stood at $85.0/t, CFR southern China port, dropping $4.7/t compared with the previous week. The CCI 4700 Import index was down $0.5/t on the week at $72.0/t, while the CCI 3800 Import index was unchanged at $53.0/t.
Weekly Dynamic
Production areas saw prices fluctuate within a narrow range last week. Some mines kept lowering prices in response to growing inventories caused by a cautious buying stance among traders and power plants, as portside prices remained on a downtrend. A few mines offering competitive prices reported increased truck arrivals, which encouraged them to raise prices slightly.
The overall supply dropped, as a few mines halted or reduced production after completing their annual output targets. Sxcoal's tracking data showed that the combined capacity utilization of the surveyed mines in Shanxi, Shaanxi, and Inner Mongolia dropped 4.24 percentage points from the previous week to 84.6% during the week ended December 24, and their output slid 4.77% to 15.41 million tonnes. Inventory shifted to a downtrend, dipping 2.75% on the week to 4.07 million tonnes.
On the demand side, slightly increased demand from non-power sectors boosted hauling activity at some high-cost-effective mines. Power plants, however, still prioritized long-term contract fulfillment, only releasing orders on an as-needed basis.
As the year-end approaches, anticipated supply-side contraction has made suppliers more resistant to further price cuts, leading to a temporary standoff between buyers and sellers. A top miner maintaining its purchase prices of third-party coal sourced from production areas unchanged also prompted expectations of prices moving within a more narrowed range this week.
Sxcoal's tracking data showed that the number of mines raising prices increased while those cutting prices decreased. Data showed that 40 out of the surveyed 160 thermal coal mines cut prices by 32.1 yuan/t averagely during December 18-24, compared with 59 mines lowering prices by 30.8 yuan/t last week; 12 mines raised prices by 12.5 yuan/t, compared to one mine hiking prices by 10 yuan/t a week ago. The remaining 108 mines kept prices flat.
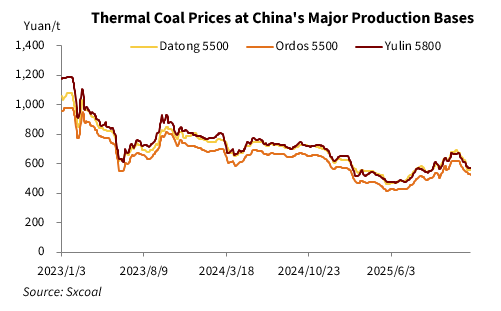
On December 26, Sxcoal assessed Yulin 5,800 Kcal/kg NAR thermal coal at 573 yuan/t, mine-mouth with VAT, slipping 2 yuan/t from the preceding week; Ordos 5,500 Kcal/kg NAR coal decreased by 14 yuan/t to 525 yuan/t; and Shanxi Datong 5,500 Kcal/kg NAR coal was assessed at 555 yuan/t, unchanged from the previous week.
Coal deliveries through Daqin railway, a major transport artery connecting production areas to northern ports, dropped further by 4.7% week on week to 1.02 million tonnes during the week ended December 26. China Railway Hohhot Group, which supervises the rail networks in central and western Inner Mongolia, approved 22 trains to transport coal each day on average last week, dipping 2 compared with a week earlier.
Portside market Spot prices at northern China ports continued their downward trend, though the pace of decline further narrowed.
A modest increase in utility tenders for domestic coal and spot inquiries, combined with growing reluctance to undersell among sellers, led some traders to withhold stock in anticipation of improved demand, slowing the downward momentum.
Participants noted that demand mildly increased, especially as stabilizing mine-mouth prices made low-priced sources harder to procure, suggesting price decline may further narrow in the near term.
Looking ahead, ample supply from January's release of capacities halted in December, high northern port inventories, and low power plant loads suggest limited improvement in the oversupply situation, leaving prices vulnerable despite any stabilization.
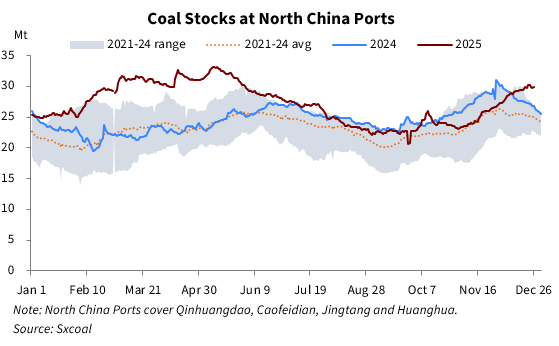
The combined inventories at Qinhuangdao, Jingtang, Caofeidian, and Huanghua ports accumulated at an even slower pace. The total stocks reached 29.87 million tonnes on December 26, climbing 0.74% from the previous week. That, however, increased 12.86% and 11.71% respectively from a month ago and the year prior, far exceeding the 2022-2024 range.
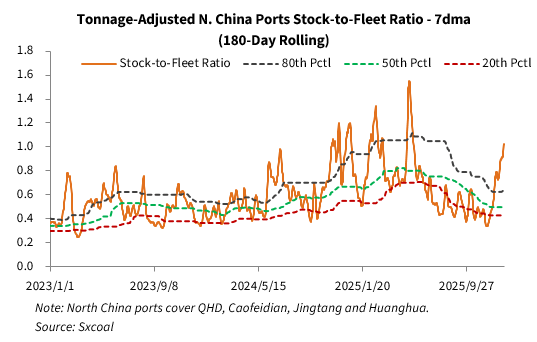
The tonnage-adjusted stock-to-fleet ratio, a major gauge for on-sight supply at northern ports, extended the rise, climbing by 0.12 to 1.01 on December 26, which exceeded the six-month rolling 80th percentile by nearly 60%, according to Sxcoal's assessment, indicating further worsening of the market situation.
The average coal burn at inland power plants, which are mainly fed by domestic supplies, stood at 4.04 million tonnes on December 24, 6.1% lower compared with the year-ago level, despite a 2.2% week-on-week increase and a seasonal monthly rebound of 21.7%.
Hydropower generation still hovered at a seasonal trough, giving support to coal-fired power during times of rising power demand. Sxcoal's data showed that water outflow through the Three Gorges dam, a key indicator of China's hydropower generation, inched up 0.5% from a week ago to 6,550 cu.m/s on December 26. That was down 31.3% from the preceding month and 6.2% compared with the preceding year.
Import market presented divergent trends between low-CV and high-CV grades. Prices of Indonesian low-CV resources remained generally stable, as falling seaborne freight rates coupled with the strengthening of the Chinese yuan offset firm offers from Indonesian miners, leaving this grade still appealing to some Chinese utilities.
Offers of 3,800 Kcal/kg NAR coal were heard stable at around $47.5-48/t FOB. Chinese traders' bidding prices to utility tenders hovered below 420 yuan/t CFR China with VAT, while a southern utility bought the same-CV cargoes through tenders at 419 yuan/t, translating to about $46.4/t FOB on a Panamax basis.
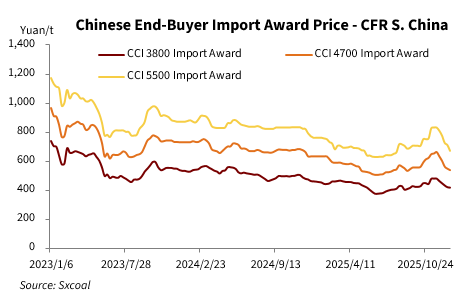
On December 26, Sxcoal assessed the utility tender-winning prices for 3,800 Kcal/kg NAR coal at 420 yuan/t CFR South China with VAT, falling 3 yuan/t compared with 423 yuan/t in the preceding week.
Uncertainties lingered, as the Indonesian government planned to impose coal export duties from January 2026, yet details about the formula and regulations remained unclear. Meanwhile, supply from Indonesia is likely to improve in January amid the approved RKAB mining quota.
High-CV coal remained under downside pressure due to ample supply and sluggish demand. A cargo of Australian 5,500 Kcal/kg NAR coal was heard changed hands at $68/t FOB, translating to about 620 yuan/t CFR with VAT South China, well below costs at around 650 yuan/t, highlighting selling difficulties.
Coal consumption at coastal power plants, major consumers of seaborne imported coal, presented an accelerated pickup of 8.6% from a week earlier and a 19% month-on-month rise. It was flat compared with the year-ago level, data showed.
As domestic prices dropped fast, imported low-CV coal registered a narrower price advantage. Sxcoal's calculation showed on December 26 that Indonesian 3,800 Kcal/kg NAR coal enjoyed a delivered-to-South China advantage of 9.3 yuan/t against domestic 4,500 Kcal/kg NAR coal on a CV-adjusted basis. That spread narrowed sharply by 19.95 yuan/t week on week and 63.71 yuan/t from the preceding month.
Australian 5,500 Kcal/kg NAR coal was 31.3 yuan/t cheaper compared with the domestic equivalent, yet this advantage was dwarfed by the overall sufficient supply.
Forecast
China's domestic thermal coal price decline at ports is expected to further narrow this week, while the mine-mouth market may witness regional stabilization backed by supply contraction and demand rebound. The import market for low-CV coal is anticipated to stay stable, supported by firm cost support and utility demand, while the downside pressure for high-CV grade is anticipated to ease.


 No Content

