


Weekly: China's coastal coal freight rates stay low amid loose vessel supply (Dec 22, 2025)
- Price
- Ports
- Consumption
- Stock
- Transport
- China
- Coal
- Logistics
sxcoal.com503 words23 reads


China's coastal coal freight rates remained at low levels last week. Despite slight rebounds, weak demand and ample vessels provided only fragile support for freight rate increases.
The China Coastal Coal Freight Composite index, which tracks rates for vessels carrying coal from northern China ports to ports in the east and south, dipped 0.78% from the week before to 633.1 points on December 19, according to the Shanghai Shipping Exchange. It also plunged 37.22% on the month and 9.5% from a year ago.
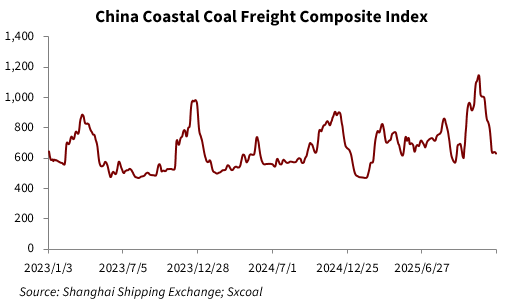
As the cold wave impacts dissipated quickly, temperatures across China returned to relatively warm levels last week, particularly in the southern regions, where temperatures reached new highs of the same periods. This limited the upside space for coal burns at power plants.
Meanwhile, the coal market extended the downward trend. End users stayed on the sidelines, slowing procurement amid a bearish outlook. Some routine shipments planned for the end of the month were also postponed.
Data showed that the number of anchored vessels at northern ports dropped to relatively low levels again. Excessive vessel capacity continued to weigh on freight rates.
However, adverse weather-induced port closures later in the week disrupted vessel turnover, modestly alleviating the supply-demand imbalance. This, coupled with cost-level freight rates, prompted vessel owners to hold firm on their offers. As a result, declines in shipping rates narrowed, and some routes saw minor rebounds along with slightly increased shipping demand.
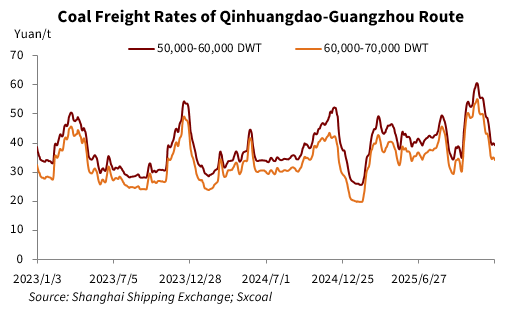
During last week, most shipping routes dropped 0.1-0.7 yuan/t compared to week-ago levels. The freight rate for the 50,000-60,000 DWT vessels carrying coal from Qinhuangdao to Guangzhou port ticked down 0.2 yuan/t week on week to 39.3 yuan/t on December 19, while that for 60,000-70,000 DWT vessels on the same route edged down 0.3 yuan/t from a week ago to 34 yuan/t.
Internationally, the Baltic Dry Index (BDI), tracking rates for ships carrying dry bulk commodities, stood at 2,023 points on December 19, down 8.25% from 2,205 points a week ago.
The Asian thermal coal market remained sluggish last week due to declining Chinese domestic prices and elevated inventories. Panamax vessels from Indonesia to China stood at $6.84/t on December 19, down $1.30/t from the previous week. Supramax freight rates from Indonesia to China reached $8.96/t, down $0.55/t from a week earlier. Meanwhile, Capesize vessels from Australia to China dipped $0.15/t week on week to $15.70/t.
Decreasing coal prices prompted traders to resist further price cuts. This, coupled with tight mine-mouth supply as the year-end approaches and disruptions in the imported coal market, eased pessimistic sentiment. Short-covering inquiries and essential needs helped drive some vessel bookings, offering modest support for the coastal transport market.
Nevertheless, persistent low power loads and relatively high inventories at power plants make a significant rebound in procurement unlikely in the near term. The overall supply-demand imbalance remains difficult to reverse, meaning freight rates are likely to stay rangebound at the bottom for the foreseeable future.


 No Content

