


Chinese thermal miners test price upticks, yet offtake pressure persists
- Opinion
- Price
- China
- Thermal Coal
- Coal
sxcoal.com585 words42 reads


China's domestic thermal coal market saw mixed movements on December 18. While a handful of mines, backed by slightly improved offtakes and expected production pullback, tested minor price increases, the broader market still grappled with tepid demand and mounting inventory pressure, capping significant gains.
Some mines, particularly those that previously slashed prices, reported modestly increased shipment volumes. This, combined with possible output curtailment at a growing number of mines meeting annual goals, encouraged them to hold offers firm.
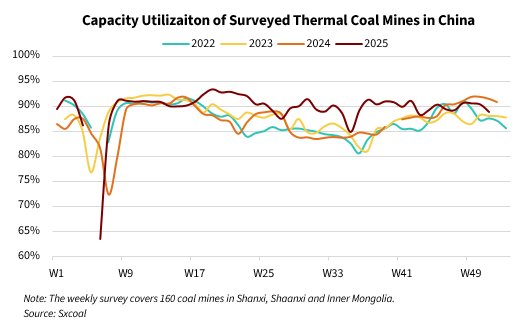
According to Sxcoal's latest weekly survey covering 160 thermal coal mines in Shanxi, Shaanxi, and Inner Mongolia, the capacity utilization of sampled mines averaged 88.81% in the week ended December 17, down 1.49 percentage points week on week, somewhat capping regional supplies.
A miner in Inner Mongolia's Ordos raised prices by 10 yuan/t, with 3,800 Kcal/kg NAR slack coal (S 0.9%) reaching 250 yuan/t, mine-mouth with VAT. "There's a bit more activity from long-haul trucks recently, besides certain demand from railway station-based traders," he pointed out, attributing part of the change to transport disruptions from recent snowfall, which affected truck arrivals for 3-4 days.
The sentiment was echoed in other mines. A second miner source noted increased truck loadings and order inquiries following 7-9 yuan/t price reductions today, suggesting a potential stabilization in the short run.
A few traders hence started to make bottom-fishing restocking given relatively low prices, although a source in Shaanxi's Yulin confirmed "the volume remained limited".
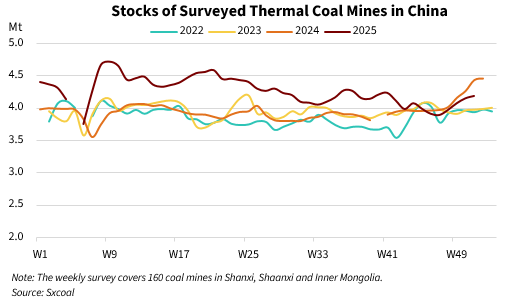
However, expectations of a large-scale price rebound were effectively capped by elevated inventories across all supply chain segments. Coal stocks at Sxcoal-surveyed mines reached 4.19 million tonnes on December 17, up 0.89% on the week. Chemical plants only made small, essential buys, and railway station-based traders still sat on the sidelines, curbing mine destocking.
As such, the market saw more price reductions than increases, with declines typically hovering around 5-30 yuan/t today. A Zhunger-based miner cut prices for 5,700 Kcal/kg NAR slack coal by 20 yuan/t to 570 yuan/t with VAT, following a 16-18 yuan/t decline in third-party coal buy prices by a leading Chinese miner starting December 17.
In Shaanxi's Yulin, though a few auctions settled higher, overall lukewarm transactions continued to weigh on the market. 4,300 Kcal/kg NAR mixed coal was heard concluded at 358 yuan/t with VAT on December 18, down 17 yuan/t from the last auction.
Such discounts reflected a market consensus that current end-user demand was insufficient to absorb relatively ample supply. Power plants, sitting on high inventory buffers with consumption dampened by warmer-than-expected nationwide temperatures, were in no rush to secure spot supplies. The persistent price advantage of imported coal further suppressed buying enthusiasm for domestic spot cargoes.
According to the National Meteorological Center, cold air activities will be frequent across China over the next 10 days, but the intensity will weaken. This may translate to a year-on-year decrease in coal consumption at power plants, even with possible sequential growth.
With prevailing cautious stance among participants, the market is likely to continue probing for a bottom throughout late December, with any potential stability or rebound highly dependent on further supply-side constraints and substantial demand recovery.
On December 18, Sxcoal assessed Datong 5,500 Kcal/kg NAR coal at 560 yuan/t, mine-mouth with VAT, down 5 yuan/t on the day, while Ordos 5,500 Kcal/kg NAR material dipped 1 yuan/t to 544 yuan/t. Yulin 5,800 Kcal/kg NAR grade declined 5 yuan/t to 578 yuan/t.


 No Content

