


Summit Focus | Global seaborne coal trade growth potential limited 2025
- Price
- International
- Event
- Global
- Coal
sxcoal.com422 words45 reads


The trading liquidity in the global seaborne coal market is unlikely to see another steep rise this year, mainly owing to restrained coal demand from power generation and main suppliers' restrictions, said an industry analyst at a market summit on February 26.
Khoo Pat See, the senior analyst of S&P Global Commodity Insights, forecasted coal demand from major importers like China and India will be hard to grow substantially in 2025, given sufficient domestic supplies, at the 2nd China Coal Import International Summit 2025 in Guangzhou.
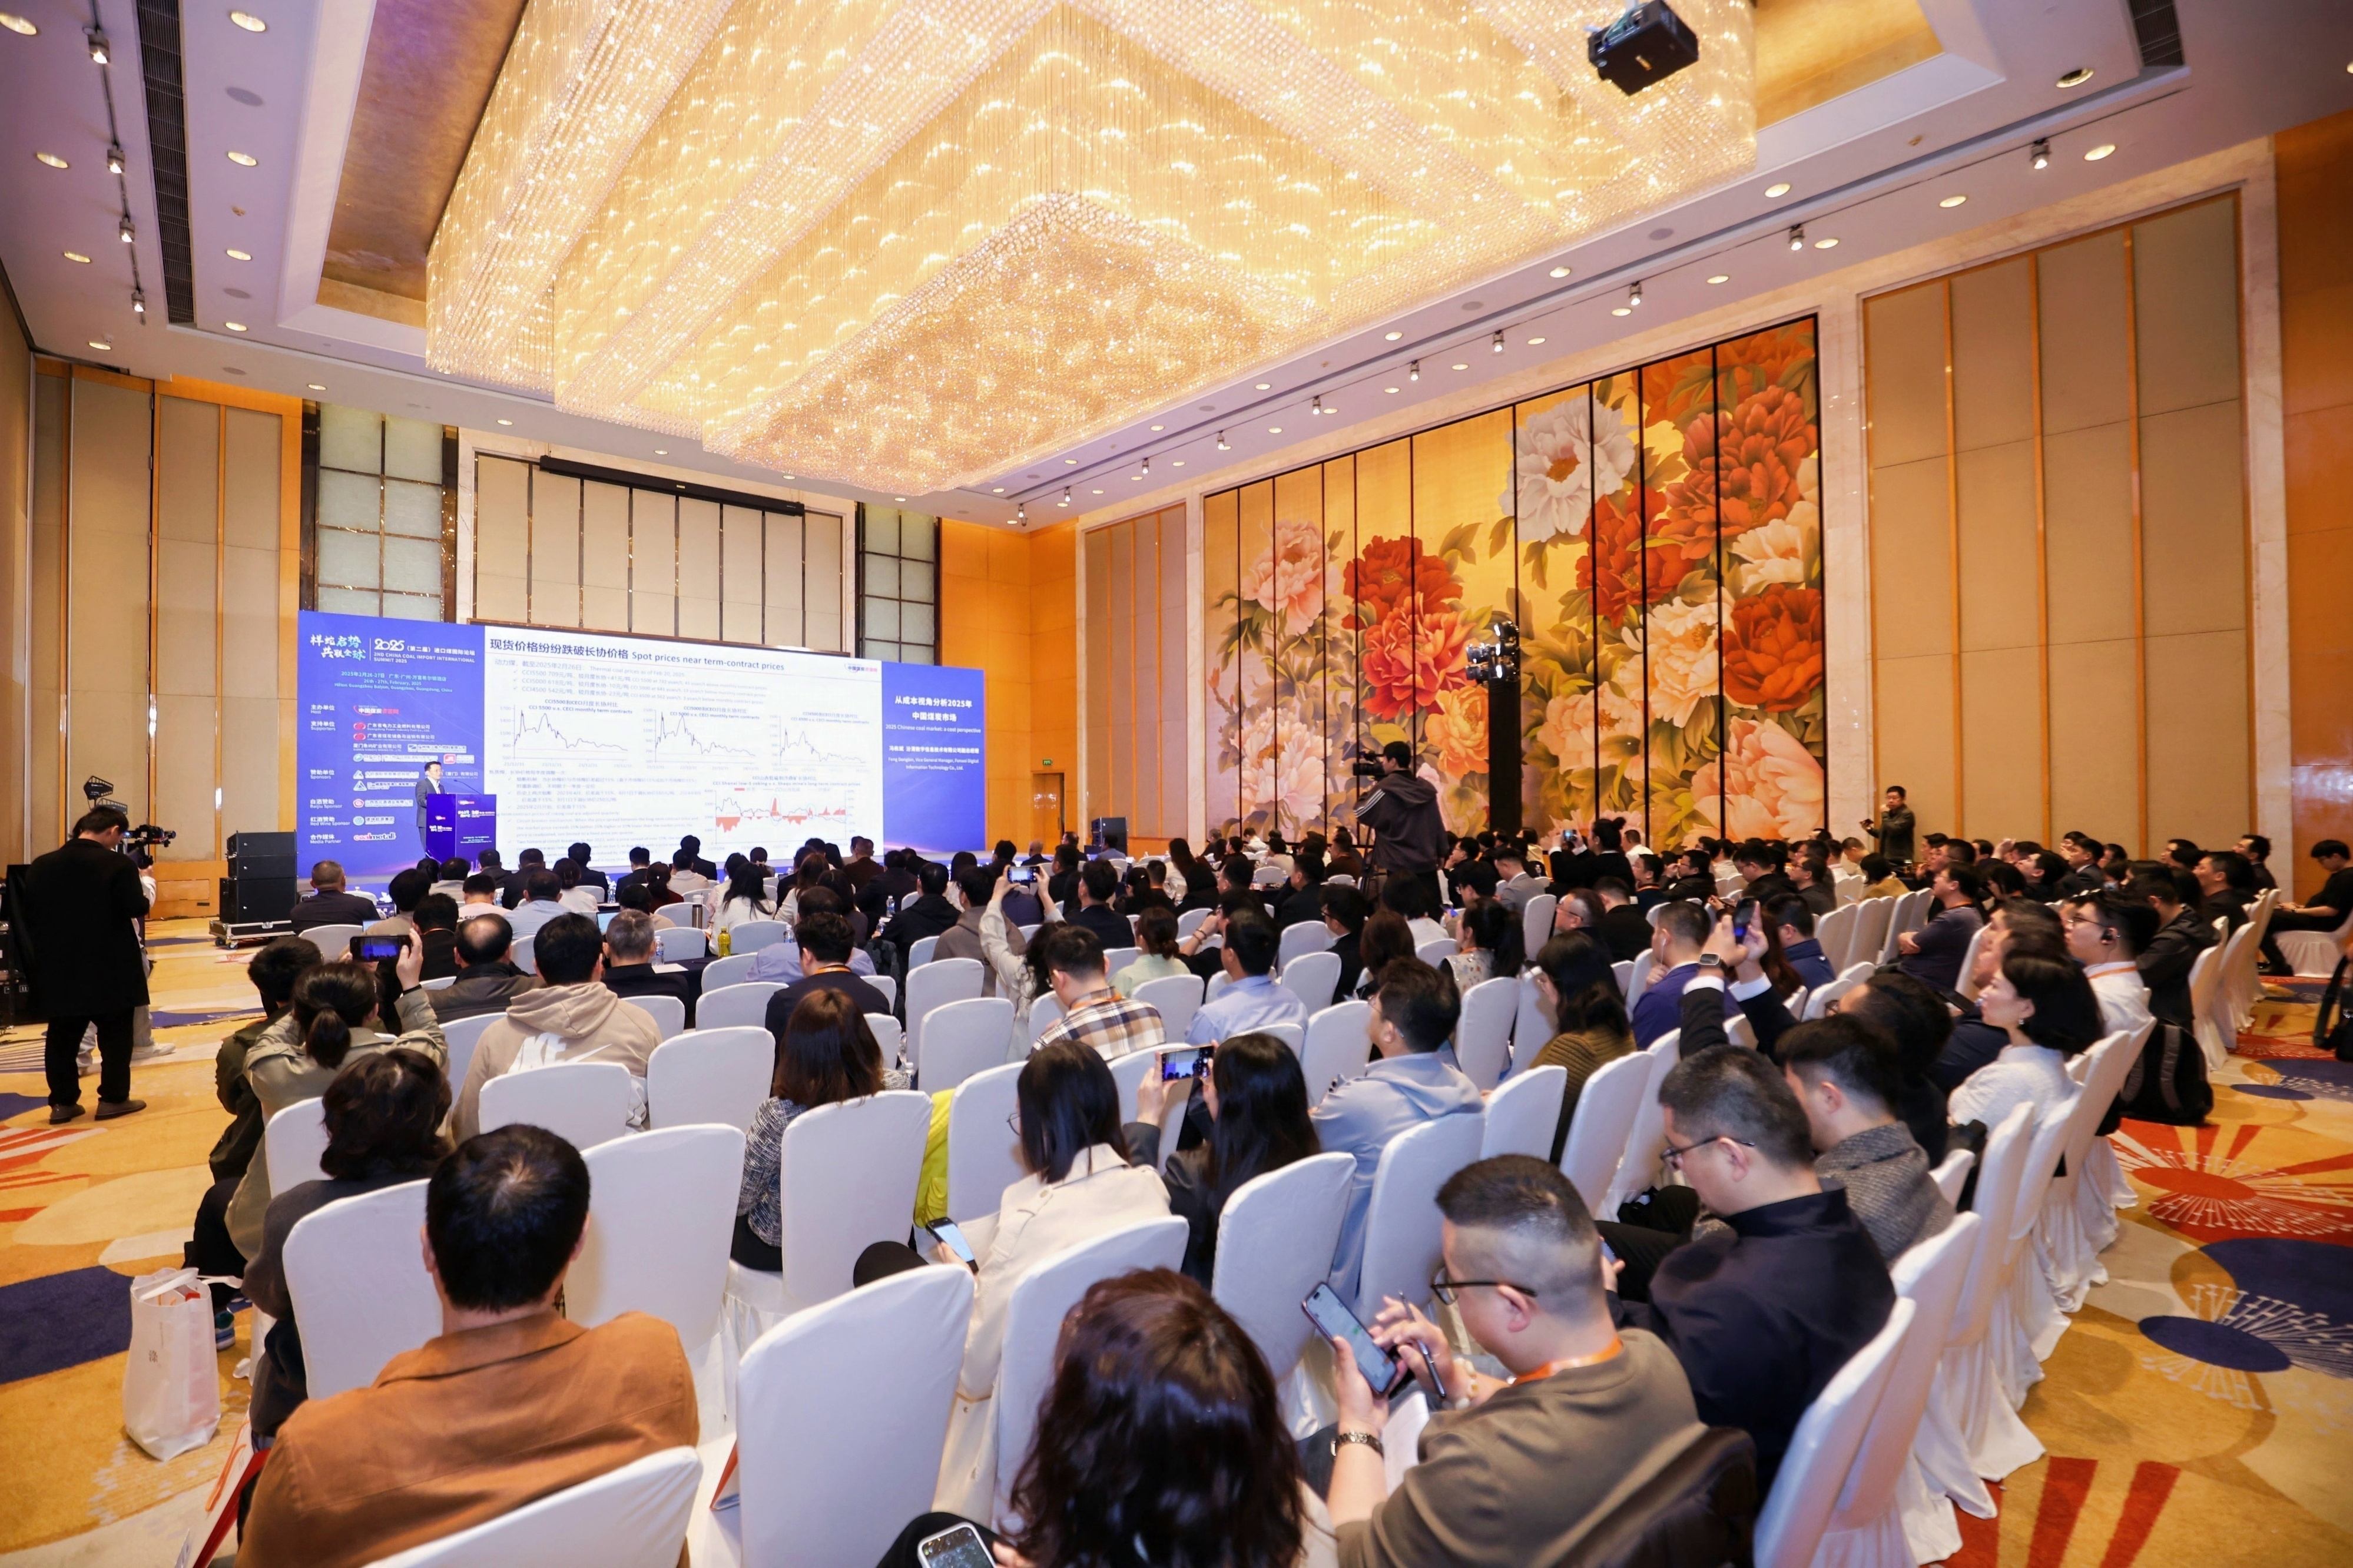
Khoo estimated China's electricity will rise 6.3% in 2025, lower than 7% in 2024, while that in India will decline from 7% to 6.5% this year. Power demand in Japan may remain steady, while the growth rate of South Korea will decrease from 2% in 2024 to 1% in 2025.
The European Union members' reliance on economic natural gas for power generation increased in 2024, directly resulting in a contraction of 40% in the region for power demand.
In 2025, their power demand is projected to rise to 2%, which may be met by increases in the installed capacity of renewable energy.
Thermal coal is increasingly subjected to seasonal changes along with rising renewable capacity. China's power generation from the fuel is stabilizing and is expected to move sideways in 2025. Compared with other Asian countries, India is likely to grab the steepest increase in power generation in 2025.
Japan and South Korea are likely to see quite steady increases, while Vietnam and Bangladesh will maintain positive territory.
Khoo accordingly anticipated China will have weaker thermal coal demand in 2025, and European countries will see similar demand trends. While India keeps increasing imports, Japan, South Korea and China's Taiwan are set to sustain steady pullups.
For suppliers, Australia's thermal coal imports are hard to further climb and may reduce from the 2024 level in 2025.
However, Indonesia still has the potential to further advance exports to 535 million tonnes this year. While Colombia and South Africa will maintain steady increases in coal exports, their main destinations will be switched to the Asian-pacific region.
The gains of U.S. coal exports will be offset by reductions from Russia and Egypt and other suppliers around the Atlantic.
In addition, intensified trade frictions are poised to lead to higher inflation, potentially curbing coal demand and dragging down coal trading liquidity.
But more frequent extreme weather will highlight price edges of seaborne coal, and coal demand will be supported by energy transformation and push up the trading volume, Khoo said.


 No Content

