


Weekly: China's thermal coal prices stabilize as resistance and inquiries grow
- Price
- Import
- Production
- Stock
- Thermal Coal
- Coal
sxcoal.com1346 words42 reads


China's domestic thermal coal prices began to rebound moderately late last week, following earlier declines, driven by heightened resistance to further price cuts and increased inquiries to cover short positions.
Sentiment in the seaborne import market improved, as utilities increased tendering activity although foreign miners mostly left the market for Christmas holiday. Traders' bidding prices to utility tenders continued to reduce partly due to a significant decline in freight rates.
Fenwei CCI Index
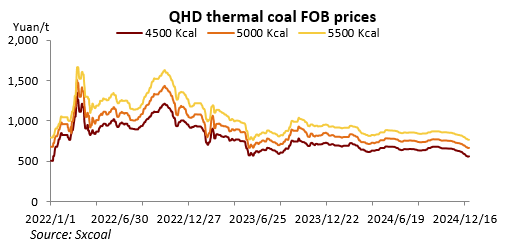
On December 27, the Fenwei CCI index for 5,500 Kcal/kg NAR domestic spot coal stood at 765 yuan/t FOB northern China ports with VAT, falling 11 yuan/t week on week. The CCI index for 5,000 Kcal/kg NAR domestic coal dropped 8 yuan/t on the week to 667 yuan/t.
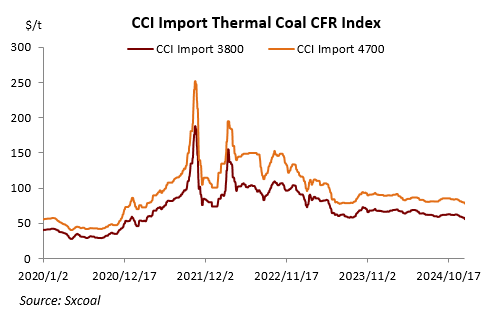
On the same day, the Fenwei CCI 5500 Import index stood at $92.7/t, CFR southern China ports, down $1.3/t from the previous week. The Fenwei CCI 4700 Import index was down $1.5/t to $78.5/t CFR, while the Fenwei CCI 3800 Import index dipped $0.7/t to $49.8/t CFR.
Weekly Dynamics
Production areas A leading Chinese coal miner maintained its buy prices for third-party coal from production areas unchanged following eight straight sessions of price cuts. The miner's pricing is an important reference for spot thermal coal prices in major production areas.
Sxcoal's weekly tracking data showed that 44 mines lowered prices by an average of 34.5 yuan/t during the week ended December 25, compared to 43 mines cutting prices by 42.3 yuan/t a week earlier. One mine raised price by 22 yuan/t while the rest 55 kept prices unchanged.
Beyond the assessment window, a few miners slightly raised prices by 5-10 yuan/t approaching the end of the week to test sentiment after receiving more inquiries.
Thermal coal supply marginally reduced, as several miners suspended production and sales after completing their annual targets. The overall capacity utilization of thermal coal mines surveyed by Sxcoal retreated by 0.98 percentage point week on week to 92.2% during the week ending December 25. Weekly output from these surveyed mines dropped 1.06% week on week to 12.45 million tonnes, Sxcoal's data showed.
Demand marginally improved, as railway station-based traders increased inquiries and a few miners reported increased arrivals of trucks for loading. However, most buyers stayed cautious in purchasing following price upticks.
Inventories, therefore, stayed flat. The combined stocks held by these surveyed mines gained marginally by 0.06% week on week to 3.47 million tonnes on December 25.
The daily rail coal delivery through Daqin railway, a major line connecting the production area in Shanxi to the northern port of Qinhuangdao, continued to slide, retreating by 3.7% week on week to 1.11 million tonnes on December 27, Sxcoal's data showed.
China Railway Hohhot Group, which supervises the railway network in central and western Inner Mongolia, approved a total of 18 trains to transport coal each day on average during last week, down 5 compared with a week earlier.
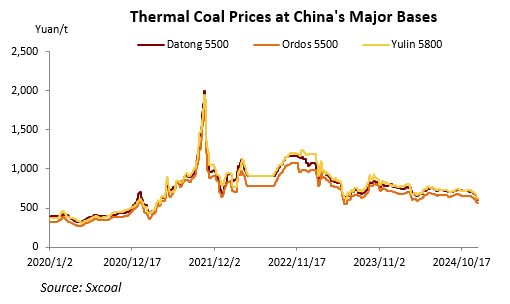
As of December 27, Fenwei assessed Yulin 5,800 Kcal/kg NAR thermal coal at 617 yuan/t, mine-mouth with VAT, falling 22 yuan/t from a week ago; Ordos 5,500 Kcal/kg NAR coal was assessed at 566 yuan/t, declining 5 yuan/t week on week; and Shanxi Datong 5,500 Kcal/kg NAR coal was assessed at 608 yuan/t, sliding 22 yuan/t during the same period.
Portside market Thermal coal prices presented a "V-shaped" trend last week, with prices rebounding in the second half given by reduced inventory pressure, strong resistance against price cuts, and increased bargaining hunting and demand to cover short positions.
The overall coal inventory at Qinhuangdao, Jingtang, and Caofeidian ports dropped further amid continued destocking efforts and reduced rail coal inflows. On December 27, the combined coal stocks stood at 24.50 million tonnes, marking a 4% decline from the week-ago level and a 10.43% fall from a month earlier. It was also 2.41% lower than the year-ago level, Sxcoal's data showed.
However, some participants questioned the sustainability of this round of price rebound, given the limited improvement in coal burns at power plants and continued sufficient on-hand, despite the ongoing month-end short-covering demand.
Data showed on December 26, coal stocks at power plants in inland provinces, which mainly source the fuel from domestic mines, dropped 1.6% week on week and 3.5% month on month, yet still 14.6% higher compared with the preceding year.
Coal burns at these plants shifted downwards by 5.8% week on week although they were 11.2% higher month on month, indicating a low likelihood for concentrated replenishment in the near term.
Most end-users maintained moderate interest in spot coal restocking, while mainly hauling the fuel from long-term contracts.
Hydropower remained at a low level during its off season. Water outflows of Three Gorges Dam stood at 6,980 cu.m/s on December 27, edging down 0.7% week on week but up marginally by 0.1% compared with the month-ago level. It was 17.1% higher than the year-prior level but at a relatively low level throughout the year, Sxcoal's tracking data showed.
Import market Imported thermal coal price decline halted at the end of last week, partly driven by increased buying interests from major power groups and improvement sentiment in the domestic market.
Chinese traders' bidding prices to utility tenders for 3,800 Kcal/kg NAR coal continued to decline last week, with the lowest bid occurring on December 26 and netting back to $49.3/t FOB East Kalimantan. Bids received by utilities on December 27 hovered at around $50-52.5/t.
Traders lowered their bidding prices following significant decline in seaborne freight rates. Sxcoal's data showed on December 27, the freight rate for Panamax vessels on the East Kalimantan-China Guangzhou route fell to $5.48/t on December 25, falling sharply by 21% compared with the preceding month and 34.8% from a year ago. The rate for Supramax vessels also fell to $8.73/t, down by 11.2% and 12.6% respectively month on month and year on year.
Chinese power utilities turned slightly more active in floating tenders for seaborne low-CV thermal coal, despite foreign sellers currently exiting the market for holiday celebrations.
One major power group was seeking 16 cargoes totaling 1.09 million tonnes of thermal coal with delivering laycan in February and March through a tender that was closed at 10:00 a.m. Beijing time on December 27, marking the highest volume since mid-November.
As of December 27, Sxcoal assessed 3,800 Kcal/kg NAR tender winning prices at 463 yuan/t, CFR with VAT, down 2 yuan/t compared with the week-ago level of 475 yuan/t.
While foreign miners were on their holiday celebration, a few offers of the Panamax cargoes of the same-CV coal from Indonesian sellers were heard at around $51/t FOB Kalimantan. Supramax cargoes of same-CV coal were heard at $49.5-50/t, but transactions were scarce.
Some trader sources expected the recent slump in freight rates to attract a small influx of low-priced imports of low-CV coal, while activities for mid-CV and high-CV coals remained weak with subdued appetite from Chinese end users.
However, high stocks and still moderate coal burns at major coastal utilities would limit the potential for any significant increase in purchases in the near term.
Coal stocks held by power plants under six Chinese coastal power groups, which mainly import coal to meet demand, stood at 13.83 million tonnes on December 27, able to cover 15.91 days of usage. The volume slid by 0.59% week on week and 3.56% compared with the month-ago levels.
Coal burns at these plants averaged 870,700 tonnes on the same day, rebounding by 0.79% week on week, 6.61% month on month and 1.55% year on year, data showed.
Forecast
China's thermal coal prices are expected to remain stable this week due to waning bearish sentiment, ongoing month-end short-covering demand, and reduced inventory pressure at northern ports. The import market may also not decline, as domestic prices have stabilized and power companies are increasing their purchases.


 No Content

