


Int'l thermal coal prices in mixed trends as coal needs diverge
- Opinion
- Price
- International
- Thermal Coal
- Global
- China
- Coal
sxcoal.com1180 words61 reads


Global thermal coal market saw both rises and falls in prices during the past week as Japanese and South Korean buyers increased purchases of high-CV coal from Australia, while demand from China and India remained tepid for Indonesian low-CV coal.
Supply Side
Indonesia Last week, tight shipping capacity led to a surge in international freight rates, forcing sellers to lower the FOB prices of thermal coal.
As of late last week, offer prices for Indonesian Panamax 3,800 Kcal/kg NAR stood at $57.5/t FOB, while that for Panamax 4,500 Kcal/kg NAR at $78.5/t FOB.
On December 8, the CCI import 3800 index for Indonesian 3,800 Kcal/kg NAR coal stood at $57.4/t FOB, a $1.6/t fall from the previous week and down $0.1/t from the previous month; the CCI import 4700 index stood at $83/t FOB, flat week on week and down $0.5/t month on month.
It is learned that the recent congestion on Panama Canal led to a shortage of Panamax and Capesize vessels in the Pacific region. This, coupled with increased shipments of commodities like grain and iron ore, and rising demand for coal shipment from Indian buyers, has resulted in a significant increase in international shipping rates since mid-November.
Market participants remained optimistic about Chinese buyer demand in early next year. With the upcoming Christmas holidays and restocking demand before the Chinese New Year in February, Chinese buyers are expected to resume coal inquiries for import by January next year.
Indian demand also remained lukewarm as favorable weather conditions in the country buoyed domestic coal production, improving supply to power plants.
Some Indonesian miners have been fulfilling their domestic market obligations (DMO) near the year-end. This, together with rising coal demand from domestic smelters and power plants, led Indonesian miners to shift to local demand. Rainfall in some major production areas also tightened supplies to some extent.
However, insiders suggested that the supply strain is insufficient to support coal prices, given the current sluggish demand in the market.
Russia Last week, Russian thermal coal prices extended the downward trend. On December 8, Sxcoal assessed Russian 5,000 Kcal/kg NAR thermal coal at $85.5/t FOB Far East ports, down $0.5/t from a week ago; Russian 5,500 Kcal/kg NAR coal was assessed at $97.5/t, also down $0.5/t.
Australia Prices for Australian thermal coal with 6.000 Kcal/kg NAR increased to nearly $150/t on expectations of possible supply disruptions related to Cyclone Jasper approaching Australia.
As of December 8, Newcastle spot thermal coal was priced at $149.4/t, up $19.7/t from the previous week and $28.9/t from the previous month, reaching a one-month high. This was a new record since the start of October.
With lower temperatures in the northern hemisphere, Japanese and South Korean buyers increased high-CV seaborne thermal coal as they preferred coal rather than natural gas to meet power demand. Intensified tropical cyclone Jasper also prompted some buyers to pay higher prices to secure more coal.
In addition, a derailment accident occurred last week involving an empty coal train operated by Aurizon Group in New South Wales, Australia, approximately 80 km west of Muswellbrook. The accident resulted in a damaged section of the Hunter Valley coal rail network, which was out of service. The timeline for restoration is yet to be determined.
South Africa Despite logistical constraints, offer prices for South African coal remained under pressure, given rising freight rates and weaker demand for imported coal in India by improved domestic supply.
As of December 8, the Richards Bay Coal Terminal (RBCT) thermal coal maintained steady week on week at $114/t FOB, a decrease of $11.3/t compared to the previous month.
Exports through the RBCT was expected to increase 14% or 500,000 tonnes from November to 4.1 million tonnes in December. This indicated that by the end of 2023, exports through RBCT may reach 47.8 million tonnes, a decrease of 2.6 million tonnes compared to 2022, the lowest in the past 30 years due to logistical restrictions. Port inventories have also risen to a 13-month high of 4 million tonnes, up 0.4 million tonnes week on week.
The congestion issue involving coal trucks at other terminals in the Richards Bay port area has not yet improved. Suppliers have been facing high demurrage costs and profit losses. Meanwhile, the South African operator, Transnet, has only received $2.5 billion instead of the expected $5.3 billion funds from the government.
This casts doubts on the ambitious plans of the new Transnet management to address the infrastructure challenges in the port and rail systems.
Demand Side
China High import costs resulted in muted demand for thermal coal imports in China. As of late last week, the lowest bids for imported 3,800 Kcal/kg NAR thermal coal were stable at 555 yuan/t, DDP with VAT.
On December 8, Sxcoal assessed 3,800 Kcal/kg NAR coal at $68.5/t CFR South China, down $1/t from a week ago; the 4,700 Kcal/kg NAR coal was assessed at $92/t, down $0.5/t week on week; cargoes of 5,500 Kcal/kg NAR coal were offered at $111/t CFR, up $1/t week on week.
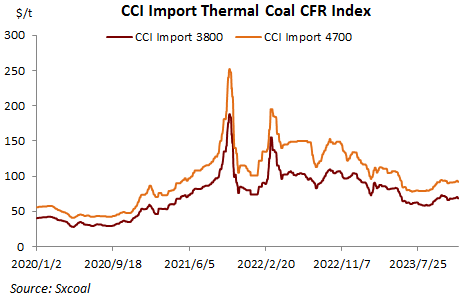
Participants said domestic buyers reported few inquiries due to the high freight rates and sufficient stockpiles at power plants. As of late last week, shipping rates for Panamax vessels eased downward, but imported coal prices remained higher than domestic coal.
Although seasonal demand would provide some support to the market, the bearish sentiment may persist in the short term with high inventory levels at ports and plants. Some importers expected the demand to rebound in mid-January next year as the Chinese New Year holiday approaches from February 10.
India Indian demand for imported coal was also weak as buyers largely relied on domestic coal with coal production ramp-up driven by favorable weather conditions.
According to data from the Central Electricity Authority (CEA) of India, coal inventory at Indian coal-fired power plants rose 6.73% from the previous week's 28.28 million tonnes to 30.18 million tonnes as of December 10. The stock was enough for 10.8 days' worth of usage, higher than the previous week's 10.1 days.
Europe Last week, the European thermal coal prices went up to around $124/t, higher than $120/t a week ago, thanks to increased consumption along with a reduction in inventories.
In Germany, the proportion of coal-fired generation in the country's energy mix rose from 10% in November to 15% in early December, while the share of wind declined from 40% to 27%.
Natural gas quotes at the European benchmark TTF hub dropped to $437/1,000 m3, down $14/1,000 m3 from a week earlier, supported by consistent supplies from Norway. Meanwhile, in early December, gas storage withdrawals increased by almost four times compared to the average November level due to cold weather across the EU.


 No Content

