


Weekly: Chinese met coke producers suffer losses amid pending 3rd price hike
- Opinion
- Price
- Coke
sxcoal.com954 words10 reads


Chinese metallurgical coke producers continued to suffer losses last week, as the third round of coke price hike has yet to materialize, while coking coal prices remained firm at high levels.
The overall coke availability increased, as traders released stocks and producers also accelerated dispatches for fear of possible demand decline in winter and transportation disruption following forecast of adverse weather conditions.
The Index
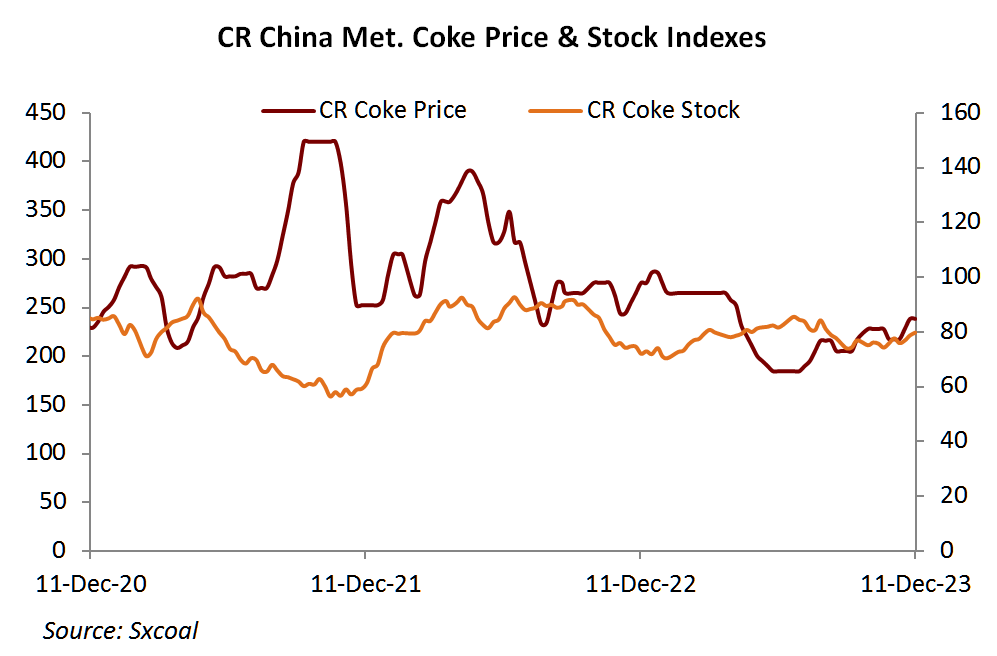
On December 11, the CR China Met Coke Price Index (CRMP) stood at 238.49 points, unchanged week on week; the CR China Met Coke Stock Index (CRMS) was up 1.25% on the week to 79.78 points on the same day.
Lately in the market
The third round of coke price hike proposed by major coke firms last week has yet to fully materialize, as major steelmakers remained muted, although a few low-stocked mills agreed to raise prices to ensure stable supply.
Many coke producers found themselves operating at or near break-even points, with some experiencing more significant losses. This was exacerbated by the upward movement in prices for certain grades of coking coal, albeit at a slower rate.
The surveyed coking plants incurred a loss of 56 yuan/t on average during the week ended on December 7, down by 11 yuan/t week on week, Sxcoal's tracking data showed.
The ongoing losses coupled with persistently high feed coal prices continued to dampen coke production enthusiasm. Besides, frequent environmental checks further constrained coke production.
As a result, coke supply remained on the downtrend last week. The capacity utilization of surveyed coking plants further dropped by 0.31 percentage point week on week to 79.83% in the week ended December 7, marking 14 straight weeks of decline since August 31, Sxcoal's data showed.
Coke stocks have fallen to a comparatively low level owing to active restocking from steelmakers. Some coking plants have been accelerating dispatches, for fear of potential downside risk.
While coke stocks continued to decline, the falling rate narrowed compared with the previous week, partly as traders' release of stocks boosted the availability in the market, which in turn weakened coke sales from production areas.
The surveyed coking plants held 167,800 tonnes of coke stocks during the week ended on December 7, falling 8% week on week and a fifth straight week of decline.
Coke demand slightly retreated last week, as some mills reduced purchases along with the increased winter maintenance schedule for blast furnaces. Survey showed an average 78.75% of furnace operating rate in the week ending December 8, sliding by 2.11 percentage points week on week.
Coke stocks held by steelmakers, however, gained marginally by 0.09 day to 10.75 days' worth of usage during the week ended on December 7, Sxcoal's data showed.
The overall coke stocks held by mills stayed at medium levels. Some low-stocked mills showed comparatively higher buying appetite for fear of possible supply disruption caused by rain and snowfall in the week.
On December 8, Luliang Quasi Grade I met coke (0.7% sulfur, 13% ash, CSR 60) was assessed by Fenwei at 2,210 yuan/t, ex-plant with VAT, unchanged week on week; that of Jinzhong Grade II met coke (0.8% sulfur, 13.5% ash and CSR 55) at 2,090 yuan/t, also flat compared with the preceding week.
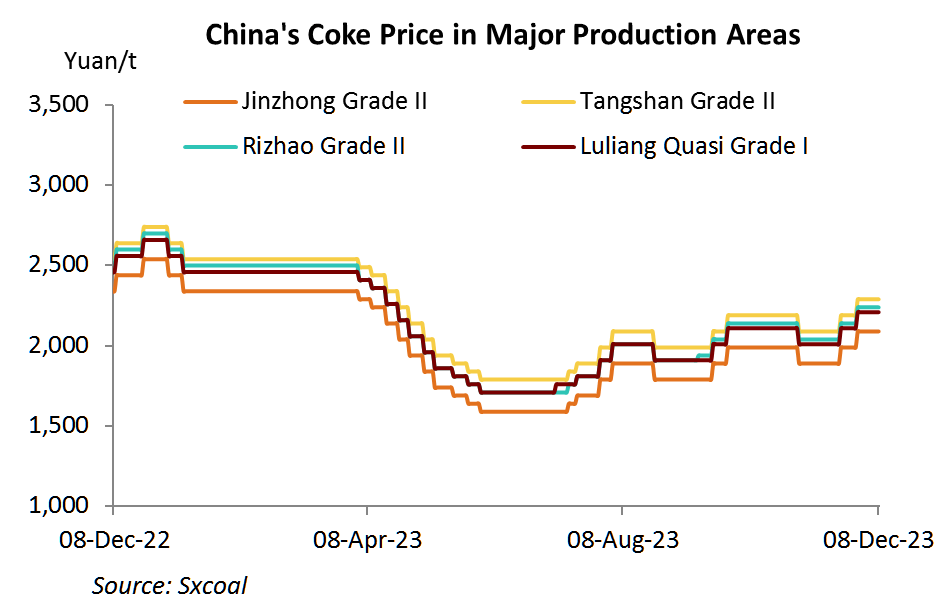
Fenwei assessed the price of Grade II met coke (0.8% sulfur, 13.5% ash, CSR 55) at 2,290 yuan/t with VAT, DDP Tangshan, steady week on week. Grade II met coke of the same quality was assessed at 2,240 yuan/t in Rizhao, DDP basis with VAT, also unchanged from a week ago.
Transfer ports
The portside sentiment weakened as participants became more cautious in taking position amid the still pending third round of coke price hike and the decline of futures prices.
More traders increased sales to secure profit last week. Spot purchases, however, remained tepid, as the sell-buy spread weighed on prices.
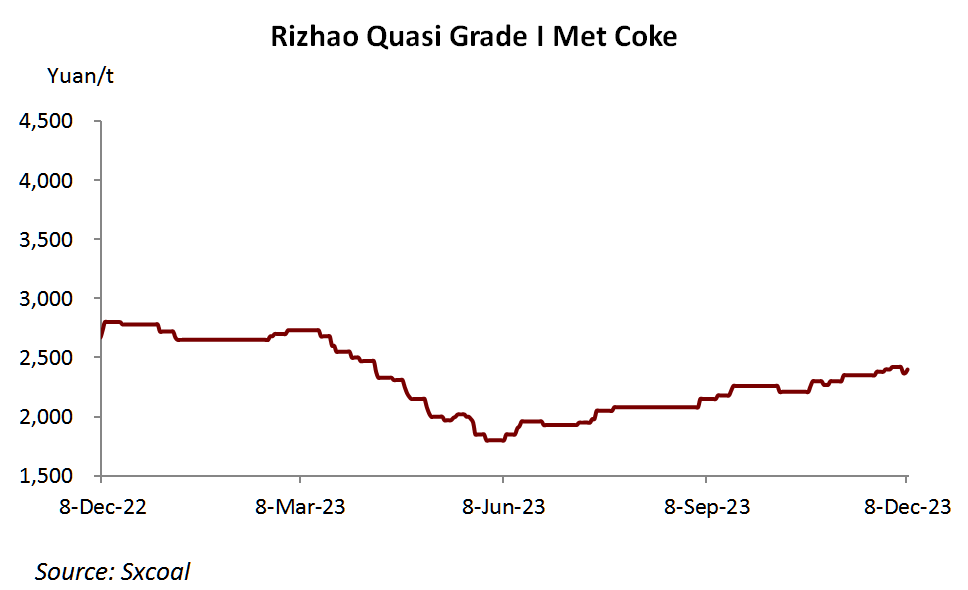
On December 8, Fenwei assessed the Shandong Quasi Grade I coke at 2,400 yuan/t, FOB Rizhao port with VAT, retreating 20 yuan/t week on week.
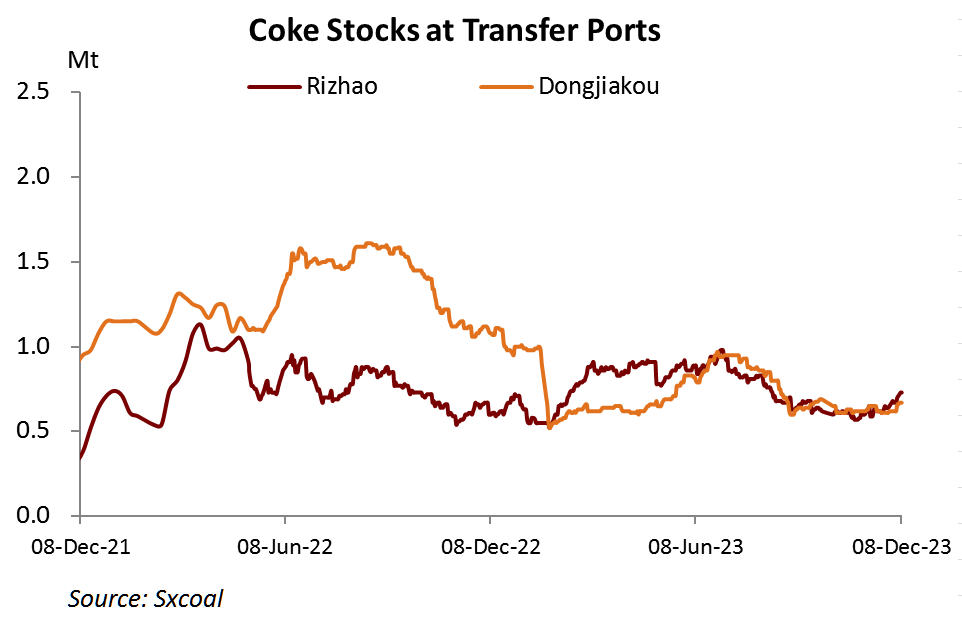
The combined coke stocks at Rizhao and Dongjiakou ports were up 8.53 % week on week at 1.40 million tonnes on December 8. That was 12% higher compared with the month-ago level but 16.7% lower than the year-ago level, Sxcoal's data showed.
Downstream market
China's steel prices rebounded last week, partly driven by resilient winter restocking demand from traders and warmer temperature-induced rebound of construction activities.
The price of Shanghai HRB 400 rebar (20 mm) stood at 4,090 yuan/t on December 8, rising 50 yuan/t from a week ago, and Shanghai hot-rolled coil (3.0 mm) was up 110 yuan/t week on week to 4,160 yuan/t. The Tangshan billet price gained 80 yuan/t to 3,710 yuan/t.
Output of five major steel products decreased by over 126,000 tonnes week on week to 9.08 million tonnes last week. The overall social stocks dropped by nearly 128,000 tonnes to 8.74 million tonnes. Daily construction steel transactions rebounded by 4.25% week on week to 149,800 tonnes, data showed.
In addition, China's new steel capacity expansion restriction policy is expected to limit the growth of steel production and benefit profits of steelmakers.
The country will no longer approve new steelmaking capacity to improve air quality and by 2025, over 80% of steel mills should complete upgrade to ultra-low emission production technology, according to a plan released by the State Council.
Forecast
The third round of coke price hike has been accepted by some low-stocked steelmakers at the start of the week, and some participants expected major mills to gradually follow suit in the following days. This expectation stems from their unyielding demand, especially amid disruptions in coke deliveries caused by logistical challenges arising from the latest snowfall.


 No Content

