


Weekly: China coking coal prices still on upward amid reduced supply
- Price
- Coking Coal
- Coal
- Coke
sxcoal.com1309 words112 reads


China's coking coal market continued to move upward during the past week, as market sentiment further buoyed by the completion of the second coke price hike and low availability of supplies at mines.
Coking coal inventories were low at most mines, owing to smooth offtakes, with some mines reporting more pre-sold orders. Trade prices for low-sulfur primary coking coal in Shanxi have increased to 2,550 yuan/t, touching the high level around the start of 2023.
The Index
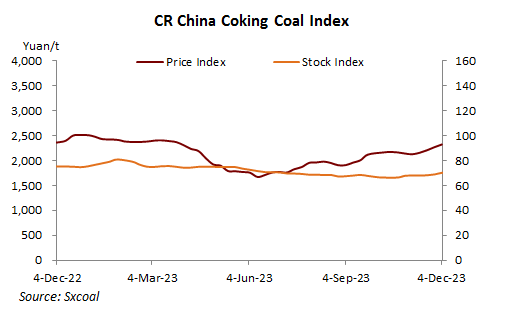
The CR China Coking Coal Price Index (CRCP) was 2,324.1 yuan/t on December 4, up 2.41% from a week earlier. The CR China Coking Coal Stock Index (CRCS) was 71.3 points, up 0.99% week on week.
Lately in the market
The overall capacity utilization at coking coal mines surveyed by Sxcoal fell by 2.81 percentage points week on week to 82.49%, and raw coal output at these mines decreased 283,300 tonnes week on week to 8.31 million tonnes over November 24-30.
The supply further contracted as intensifying safety inspections in key production areas, triggered by frequent mine accidents, led to growing production cuts and mine suspensions. Additionally, some major mines, closing to completion of their annual targets, were proactively reducing production.
Washed coking coal stocks at the surveyed mines decreased by 128,500 tonnes week on week to 1.31 million tonnes this week, while raw coal stocks reduced by 172,900 tonnes to 1.75 million tonnes.
The continued decline was attributed to the good buying appetite from coking plants that saw improved profitability after the second price hike. Middlemen also presented active purchase amid still optimistic sentiment over the near-term coke prices.
Against the backdrop of supply-demand imbalance, miners were experiencing smooth sales, with inventory continuing to slide. Coking plants saw their feed coal arrivals decline as supply was tightened by the recent mine accidents. Coking coal stocks held by the surveyed coking plants dipped by 0.3 day week on week to 7.51 days of usage.
Coking coal mines halting operations for mine accidents still haven't resumed normal operations during the past week, while some mines in Lishi were asked to stop double face mining operations, further restraining regional production and supply and buoying local coal prices.
In Luliang, one auction for 30,000 tonnes of low-sulfur primary coking coal (S 1%, A 11%, GRI 85) settled higher at 2,570-2,575 yuan/t, refreshing recent highs, after starting at 2,100 yuan/t on November 29, while the previous trade was concluded at 2,310-2,315 yuan/t on November 15.
Another 50-yuan/t price hike was observed in low-sulfur primary coking coal (S 0.5%, GRI 80-85) in Anze of Linfen, Shanxi to 2,550 yuan/t, ex-washplant with VAT and in cash, sending total price increase in November to 300 yuan/t.
Coal prices for primary coking coal and lean coal in Xiangning climbed another 70-80 yuan/t last week, up 200-360 yuan/t compared with low points in October. Low-sulfur primary coking coal (S 0.55%, GRI 80) and lean coal (S 0.65%, GRI 70) rose 80 yuan/t to 2,550 yuan/t and 2,270 yuan/t, respectively. The low-sulfur lean coal (S 0.8%, GRI 55) offers remained steady at 1,830 yuan/t, while high-sulfur primary coking coal (S 3%, GRI 80) was also flat at 1,845 yuan/t, both on ex-washplant with VAT basis and in cash.
The same price revisions were also made by miners in Gujiao, Taiyuan of Shanxi, on November 22, and the adjusted price for low-sulfur primary coking coal (S 0.5%, GRI 85) increased to 2,450 yuan/t, ex-washplant with VAT and in cash. The total price rises in November also reached 250 yuan/t.
In Gujiao, local low-sulfur primary coking coal (S 0.5%, GRI 85) stabilized around 2,450 yuan/t, ex-washplant with VAT and in cash, and regional supply faced further shrinkage as safety inspections escalated.
In Jinzhong, offers for high-sulfur fat coal (S 1.5-1.8%, GRI 90) went up by 50-100 yuan/t to 2,350 yuan/t, ex-washplant with VAT and in cash.
Major miners in Changzhi revised up prices of washed lean coal (S 0.4%, GRI 10-15) by 80 yuan/t to 1,580-1,590 yuan/t, while washed lean coal (S 0.4%, GRI 30) and washed PCI coal (S 0.4%, GRI 0-5) stabilized at 1,330-1,350 yuan/t, all on ex-washplant with VAT basis and in cash. Prices of Qinyuan low-sulfur primary coking coal (S 0.5%, A 8.5%, GRI 83) climbed another 50 yuan/t to 2,500 yuan/t last week.
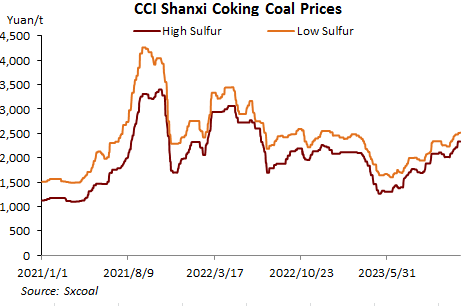
On December 1, the Fenwei CCI index for Shanxi low-sulfur primary coking coal was assessed at 2,510 yuan/t, ex-washplant with VAT, up 30 yuan/t from a week ago; the index for Shanxi high-sulfur coal rose 119 yuan/t to 2,333 yuan/t.
In Inner Mongolia, one major miner in Qipanjing concluded an online auction of low- sulfur fat coal (S 0.8%, A 12%) at 1,990 yuan/t against the starting price of 1,970 yuan/t on November 30, up 20 yuan/t compared with the previous settlement. The miner also started two auctions of high-sulfur fat coal (S 2.5%, A 12%) and high-ash fat coal (S 1.0%, A 15%) at 1,970 yuan/t and 1,700 yuan/t respectively. They were closed at 1,980 yuan/t and 1,730 yuan/t, up 20 yuan/t and down 10 yuan/t respectively.
In Shandong, the prices of washed gas coal (S 0.5%, GRI 75) rose 30 yuan/t to 1,510-1,520 yuan/t. Local coking coal miners reported declining stocks as purchases increased.
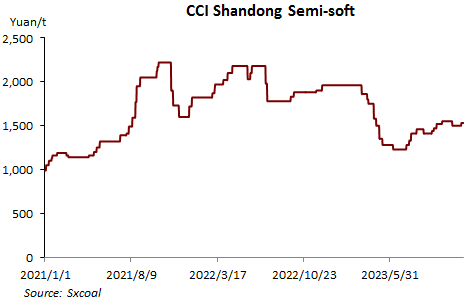
On December 1, the Fenwei CCI index for Jining gas coal in Shandong increased 30 yuan/t from last week at 1,530 yuan/t, ex-washplant with VAT.
Import market
Australian coking coal prices fluctuated last week. Low-vol hard coking coal for January-laycan rose to $325/t FOB. That translates to around 2,806 yuan/t CFR China with VAT. Spot prices for Russian coal mostly stayed flat, with K10 traded around $211.5/t CFR, equivalent to 1,710 yuan/t CFR China with VAT.
At spot market, some coking coal grades further gained support from limited supply. Yet the downstream became cautious in purchasing. Offers of spot Russian low-ash K4 coking coal were 2,350 yuan/t, ex-stock with VAT, with some higher offers at 2,400 yuan/t, up 50-80 yuan/t on the week; and Russian Inagli was offered at 1,850-1,950 yuan/t, rising 50 yuan/t.
The daily clearance of Mongolian coal at Ganqimaodu averaged 1,072 trucks during November 27-30, down by 56 trucks week on week. Last week traders maintained firm offers as short-haul shipping rates rebounded to high range. But the downstream mostly purchased on a need-to basis because of thin profits. Spot prices for Mongolian 5# raw coal accordingly climbed to 1,680-1,800 yuan/t, ex-stock Ganqimaodu with VAT, as trading liquidity improved along with higher domestic coal prices.
China's Ceke border port let in 788 trucks of Mongolian coal on average during November 27-December 1, down 34 trucks week on week. Imported coal market at Ceke also gained strength from robust increase of coking coal prices in Shanxi. Traders and washing plants both were active in restocking. Offer prices for MAK A raw coal rose 10 yuan/t week on week to 940 yuan/t and MAK West at 1,020 yuan/t, up 30-40 yuan/t week on week, ex-stock with VAT.
Mandula saw a daily average of 348 trucks hauling Mongolian coal pass through during November 27-December 1, falling 106 trucks week on week. The market gained momentum from increased coke prices. This, together with purchases for winter storage, led to moderate rise in prices of various coal grades traded at the port.
Forecast
China's coking coal prices are forecast to sustain upward growth, but at a slower pace in the week ahead, as further coke price hike proposal, if materializes, would encourage coking plants to make increased purchases for the material.


 No Content

