


Monthly: China Nov lump anthracite prices remain stable amid weak demand
- Opinion
- Price
- Anthracite
- China
- Coal
sxcoal.com600 words14 reads


China's lump anthracite market remained weak in November; supply was relatively stable, but demand lacked support amid cautious procurement from end users. The market was also impacted by facilities overhaul at some downstream industries in winter.
October supply-demand
Supply The effective supply of lump anthracite was 6.13 million tonnes in October, down 17.66% month on month. In January-October, lump anthracite supply totaled 58.47 million tonnes, up 7.17% year on year.
Demand Lump anthracite consumption was 5.73 million tonnes in October, rising 13.64% month on month. In January-October, total consumption was 48.13 million tonnes, up 3.45% year on year.
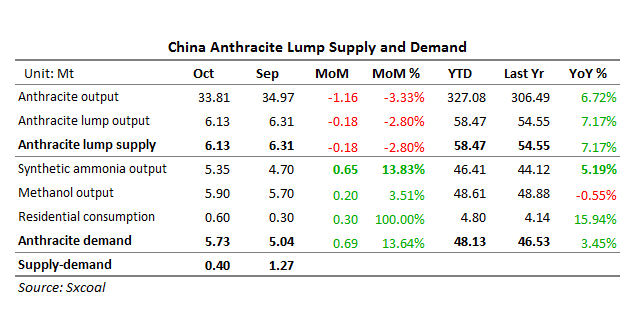
As a result, the supply surplus narrowed from 1.27 million tonnes a month ago to 0.4 million tonnes in October.
Overview of November market
Main production areas
As of late November, lump anthracite prices of three major production areas — Yangquan and Jincheng in Shanxi and Jiaozuo in Henan — stayed flat from a month ago, while prices in Yongcheng of Henan declined from a month ago.
Compared with the year-ago level, lump anthracite prices in Yangquan, Jincheng and Jiaozuo dropped by 650 yuan/t.
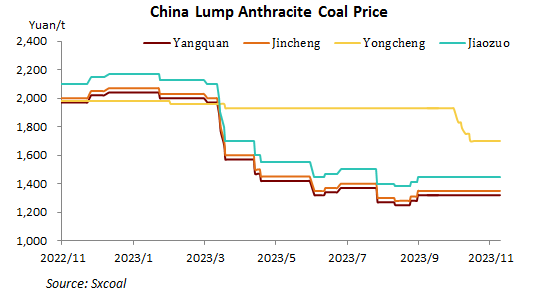
As of November 28, Fenwei assessed the price of Jincheng mid-lump anthracite (7,000 Kcal/kg NAR, 14% ash, 8% volatility and 0.5% sulfur) in Shanxi at 1,350 yuan/t with VAT, flat month on month; while small-lump anthracite with the same quality also unchanged at 1,300 yuan/t with VAT month on month.
The price of mid-lump anthracite (7,000 Kcal/kg NAR, 7% VM, 0.3% sulfur) in Jiaozuo was stable from October at 1,450 yuan/t, while Yongcheng prices dropped 90 yuan/t to 1,700 yuan/t.
The anthracite market moved downwards in Guizhou in November. By the end of November, the prevailing mine-mouth prices of mid-lump anthracite in Jinsha and Nayong stood at 1,620 yuan/t and 1,630 yuan/t, both down 60 yuan/t from the month-ago level.
Main consumption areas
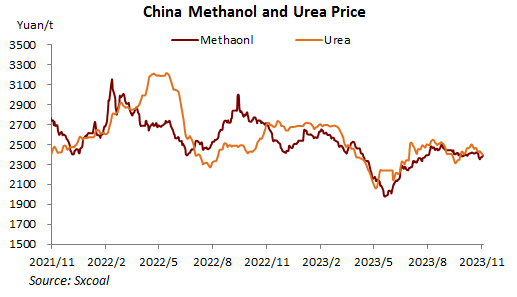
As of November 28, the methanol price increased by 3 yuan/t from the end of October to 2,392 yuan/t.
The methanol market remained stable in November. Profits of methanol enterprises slightly improved, thanks to reduced coal prices, but the methanol cost was also affected by negative factors. Some facilities that completed maintenance resumed production, slightly pulling up supply.
The methanol demand continued to weaken, owing to limited restocking enthusiasm from the downstream market.
At the same time, inventories increased at ports. Although the import is expected to contract in December, the overall import is still at a high level and the supply side is still under pressure.
The urea prices started to fall in mid-November. As of November 28, urea price was 2,397 yuan/t, down 4 yuan/t from a month ago.
Urea supply continued to increase as previously suspended facilities resumed operations. Participants were cautious about purchases as demand from the agricultural industry reduced. Industrial demand was still weak, and the export market also lacked favorable support temporarily.
Urea production is expected to maintain a high level in December compared to last year, but may decrease from the previous month due to increased maintenances.
The domestic urea market is expected to maintain a growth trend after a period of decline, and buyers would mainly restock on a need-to basis.
Summary
In November, lump anthracite prices remained stable, owing to surplus supply but weak demand. Main-producing coal mines prioritized safety, as they basically completed or close to complete production tasks for the year. The demand side generally was cautious towards procurement, and chemical plants showed no increase of purchase. Overall weakness in the coal market also dampened sentiment in the lump anthracite market.


 No Content

