


Summit Focus | China's steel demand to see a slight YoY decrease in 2023
- General
- Opinion
- Steel Products
- China
- Steel
- Event
sxcoal.com525 words5 reads


China's steel demand in 2023 is expected to be approximately 910 million tonnes, with a small year-on-year decline, due to a decrease in demand from the construction industry, Fan Tiejun, president of China Metallurgical Industry Planning and Research Institute, noted at a summit in Nanning, Guangxi on September 7.
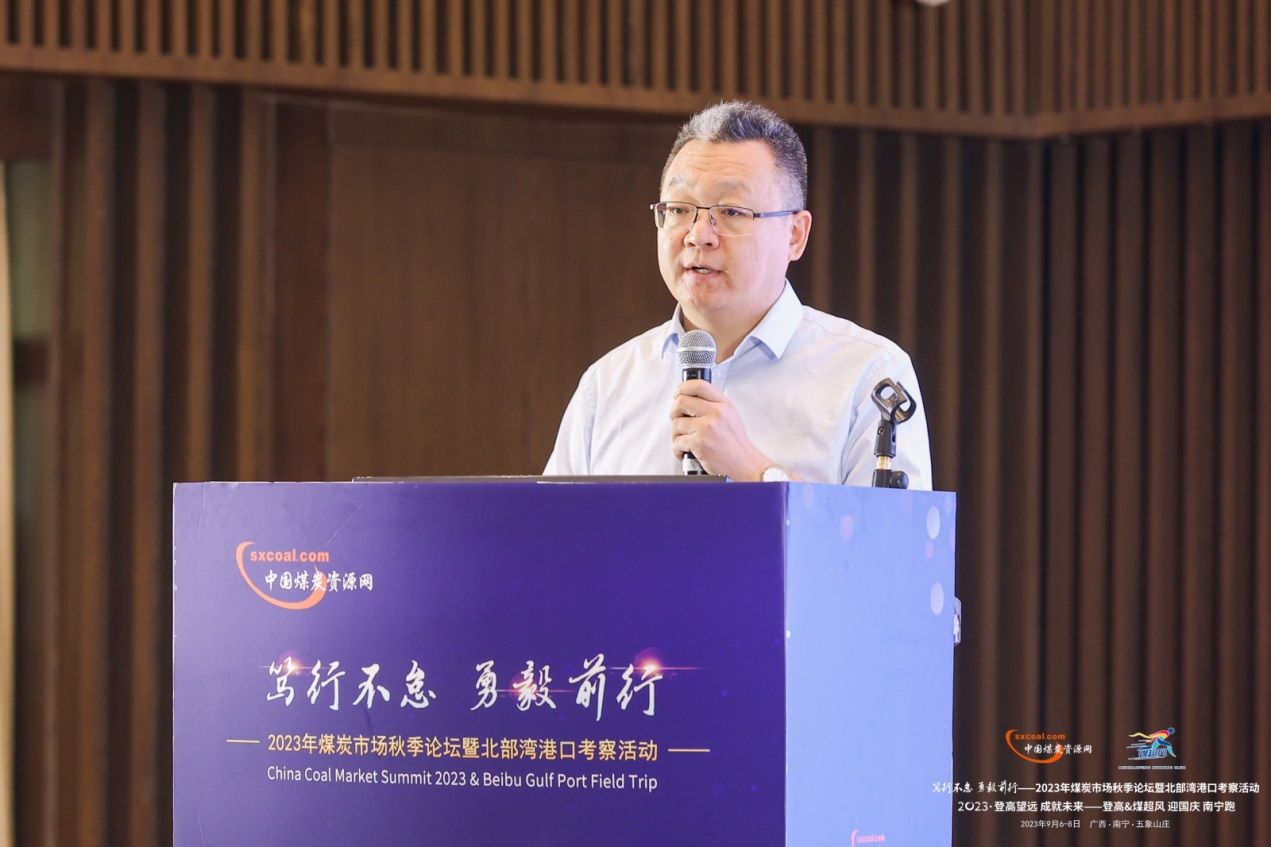
The government work report has set the economic growth target for the full year of 2023 at around 5% increase in GDP, which will help maintain high steel consumption. But the steel demand in the construction industry for 2023 is predicted to fall 2.3% from a year ago to 520 million tonnes, according to Fan during the China Coal Market Summit 2023 & Beibu Gulf Port Field Trip held by Sxcoal.
From January to July, China's steel market experienced sustained high production, a substantial increase in exports, a sharp decrease in imports, and significant decline in operational efficiency.
China produced 626.51 million tonnes of crude steel during the same period, up 2.5% year on year (YoY); pig iron output reached 528.92 million tonnes, up 3.5% YoY; steel output at 788.995 million tonnes, a 5.4% rise YoY.
Total steel exports stood at 50.89 million tonnes over January-July, up 11.10 million tonnes or 27.9% YoY, while total steel imports amounted to 4.42 million tonnes, down 2.14 million tonnes, or 32.6% YoY.
The revenue for ferrous metals smelting and rolling industry came in at 4,734.63 billion yuan (about $645.24 billion), down 7.6% YoY. The total profit plunged 90.5% YoY to 4.96 billion yuan.
During the "14th Five-Year Plan" period, China's steel demand is forecast to fluctuate downward, but the overall quantity will remain at a relatively high level.
Urbanization and industrialization in China will continue during this period, and there will be proactive infrastructure development, comprehensive promotion of consumption, and an expansion of domestic demand. These factors will play a role in stabilizing and promoting the healthy development of construction, machinery, and some other industries.
However, as China shifts its economic development model and adjusts its industrial structure, the proportion of the tertiary industry – mainly the service sector – will continue to rise, leading to a declining trend in the intensity of steel consumption. Nevertheless, the overall steel consumption quantity will remain high.
As downstream industries such as aerospace, automotive, and others continue to upgrade, the demand for high-quality steel with properties like high strength, toughness, long life, high-temperature resistance, and corrosion resistance will steadily increase. This will drive the upward trend in high-value-added steel varieties.
During the "14th FYP" period, industries such as machinery and automotive are likely to see growth in steel demand, resulting in increased consumption of products like H-beams and other finished steel. However, industries like real estate, containers, hardware products, and others will witness a decrease in steel demand, resulting in reduced demand for products like rebar, wire rod, cold-rolled sheets, color-coated sheets, and common structural profiles.
In the later part of his presentation, Fan put forward some recommendations for the quality development of steel industry under the new situation, including making high-quality development the central theme, deepening supply-side structural reform, actively promoting electric arc furnace steel production and striving to expand domestic steel demand.


 No Content

