


Summit Focus | China H2 coking coal output to be lower than H1
- Opinion
- Price
- Coking Coal
- China
- Coal
- Coke
- Event
sxcoal.com495 words8 reads


China's coking coal production is expected to decline 1-2% in the second half of 2023 from the first half due to investigations of underreporting of accidents and inspection of safety and overproduction, Liu Yanjun, manager of market research department, senior coal/coke analyst of Fenwei Digital Information Technology Co.Ltd, said at an industry summit on September 7.
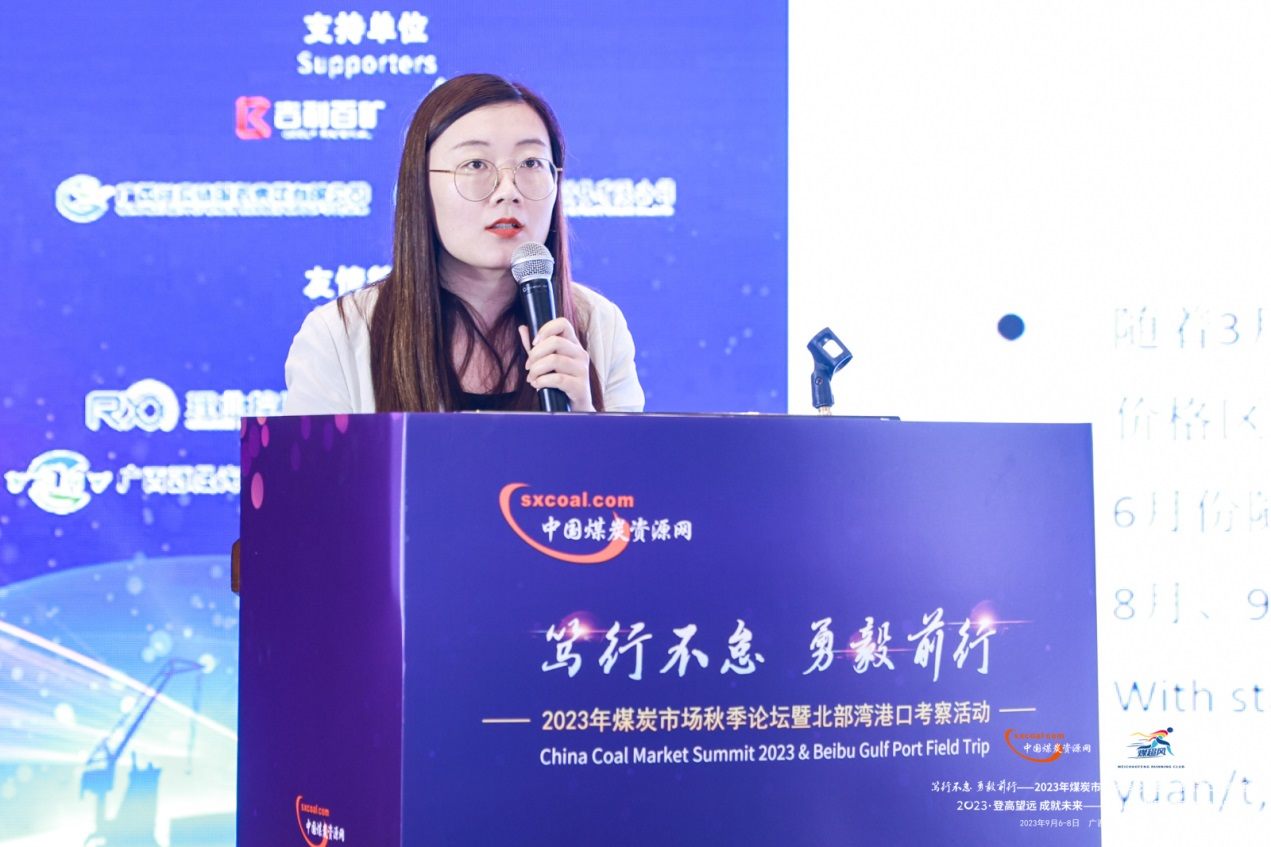
Liu analyzed the market of coking coal and coke at the China Coal Market Summit 2023 & Beibu Gulf Port Field Trip in Nanning, Guangxi. The summit was held by Sxcoal, a coal industry portal operated by Fenwei.
With stable coal supply increase in March, prices of various coking coal grades entered a significant downward trend in the main producing areas, with a general decline of around 1,000 yuan/t, and prices basically dropped to the upper edge of the price range from 2016 to 2020.
During June-July, coking coal prices increased by 300-400 yuan/t backed by rising demand for summer peak period, contracted supply in production areas and restocking from downstream users. In August and September, coal prices fluctuated and would continue to hover at a high range.
Liu predicted the lowest price level in the second half to emerge in late November, which, however, is likely to be higher than the low in the first half), and projected winter restocking to start from mid-December.
Coking coal output in July-December is expected to fall 1-2% from the first six months, equivalent to 5-8 million tonnes of raw coal reduction.
In terms of imports, total coking coal intakes in the second half are forecast to reach 46-48 million tonnes, up 1-2 million tonnes compared to January-June (washed coal).
Total raw coking coal supply is expected to decrease 10 million tonnes compared with the first half, Liu said.
As for coal demand, cokemakers are unlikely to destock substantially before October, given factors including restrained transportation during rainy season, continued coal supply, and disruption of holidays of Mid-autumn Festival and National Day.
The overall coke stocks are predicted to be higher than the first half.
Liu stated that coking coal demand will be suppressed during the second half as a whole. The demand for premium coal grades, however, is likely to further increase owing to the switch to large coke ovens with 4.3-meter ones.
Over January-March, coke prices remained stable. In the second quarter of the year, coke prices slumped by 750 yuan/t as coking coal prices declined and steel prices faced pressure. From July to September, coke prices rebounded by 300 yuan/t on the back of increased coking coal prices and higher molten iron production.
Liu expected high molten iron production to sustain for some time as long as profit margins still exist. Coke prices are likely to hover at high levels in September as it is unlikely to significantly enforce curbs on crude steel production in the month, and the support from coking coal costs before the Mid-autumn Festival and National Day would be strong.


 No Content

